With savings accounts paying little and markets regularly in the headlines, more people are thinking about investing for the first time. Financial educators say that is a sensible instinct, but only if beginners understand a few basics before they start. This guide covers general principles; it is not personal advice, and anyone unsure should speak to an independent, licensed adviser.
1. Build a safety cushion first
Before investing a single euro, make sure you have an emergency fund in an ordinary savings account. A common guideline is three to six months of essential expenses. Without it, an unexpected bill could force you to sell investments at a bad moment.
2. Understand that prices go down as well as up
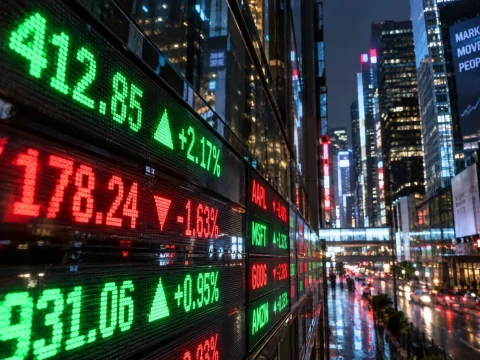
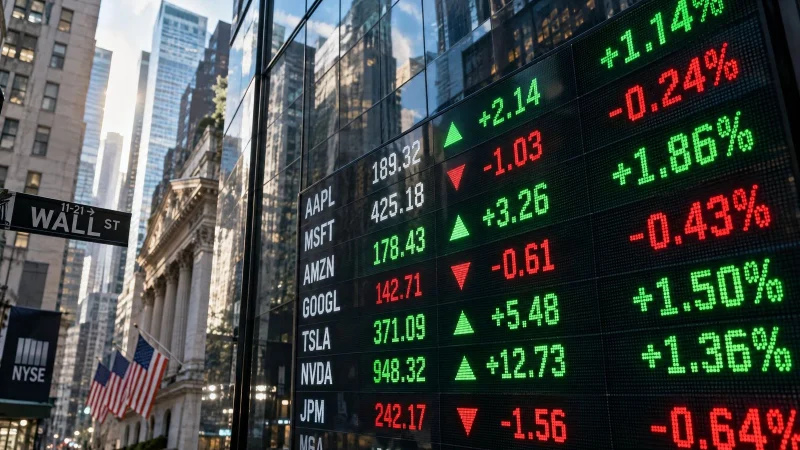
The red and green numbers on market screens are a reminder that values move every day. Shares and funds can fall sharply, sometimes for months or years.
If watching your savings drop by a fifth would keep you awake at night, that tells you something important about how much risk you can take.
Marta Ilic, financial educator at a consumer association in Riverton
Money you will need within the next few years is usually better kept out of the stock market.
3. Don’t put all your eggs in one basket
Buying shares in a single company is a concentrated bet. Spreading money across many companies, sectors and regions, for example through broad index funds, reduces the damage if one of them performs badly.

Comments 2
Clear and calm, thank you. Most articles on this make it sound much more complicated.
Point one is the one nobody wants to hear, but it saved me when my car broke down last year.